
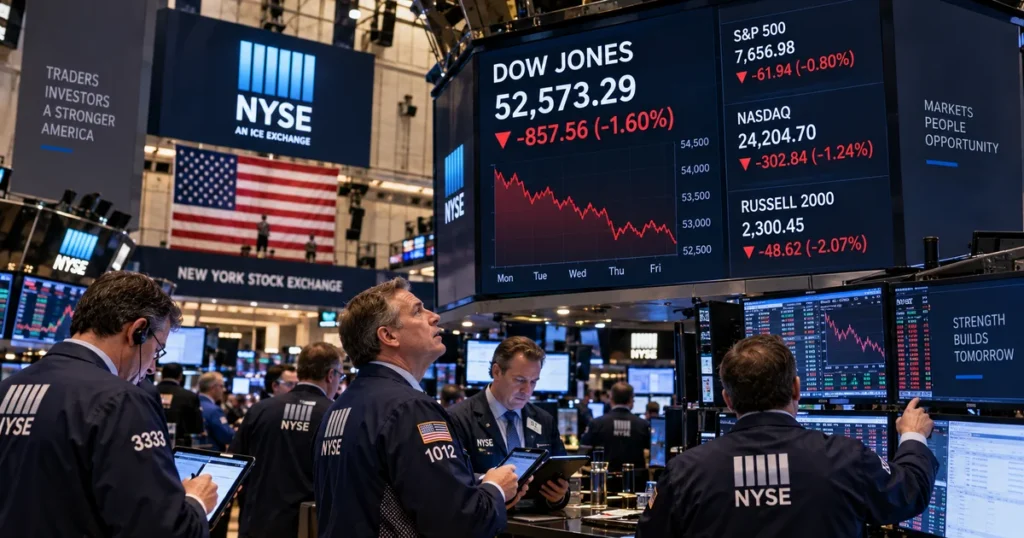
The Dow Jones this week recorded its steepest weekly decline since March 2026, falling 1.6% over the five-day period to finish Friday at 52,573.29. A sharp Friday afternoon rebound of 509.19 points (+0.98%) provided welcome late-week relief, but it was not enough to erase earlier losses triggered by energy price spikes and shifting Federal Reserve interest rate expectations.
The broader market mirrored this bifurcated dynamic. The flagship USA S&P 500 gained 65.28 points (+0.86%) on Friday to settle at 7,656.98, yet still wrapped up the week with a 0.8% weekly decline. Meanwhile, the tech-heavy Nasdaq Composite rose 251.31 points (+0.96%) on Friday to close at 26,333.04, limiting its five-day contraction to 0.7%. Across Wall Street, defensive rotations and volatility dominated portfolio positioning.
Weekly Scorecard: Wall Street Main Indices Performance
Quick Answer: How Did US Indices Perform This Week?
All four major U.S. benchmarks finished the week lower on aggregate despite a broad-based relief rally on Friday. For the full week, the Dow Jones dropped 1.6% (Friday close: 52,573.29), the S&P 500 fell 0.8% (Friday close: 7,656.98), the Nasdaq shed 0.7% (Friday close: 26,333.04), and the small-cap Russell 2000 retreated 2.4% to 2,903.94.
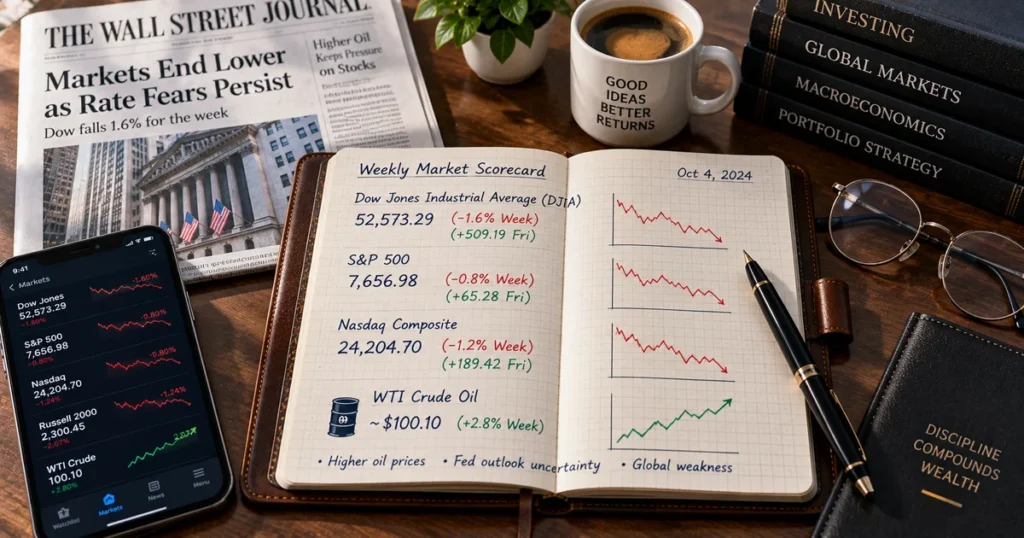
The official weekly scorecard across cash benchmarks:
| Index | Friday Close | Friday Daily Change (%) | Friday Points Change | Full Week Change (%) | 5-Week Trend |
Dow Jones Industrial Average (^DJI) | 52,573.29 | +0.98% | +509.19 pts | -1.6% | Red in 4 of last 5 weeks |
S&P 500 (^GSPC) | 7,656.98 | +0.86% | +65.28 pts | -0.8% | 3rd straight weekly decline |
Nasdaq Composite (^IXIC) | 26,333.04 | +0.96% | +251.31 pts | -0.7% | Snapped multi-week advance |
Russell 2000 (^RUT) | 2,903.94 | +0.40% | +11.50 pts | -2.4% | Underperformed large caps |
5-Week Trend: Dow Closes in the Red for Fourth Time in Five Weeks
The performance of the Dow Jones this week highlights a clear defensive pattern among mature, dividend-paying blue chips. While large-cap technology equities found selective dip-buying, the 30-stock Dow Jones has finished lower in four out of the last five weeks.
This trend reflects structural sector rotations governed by the core market forces detailed in how stock prices are determined. Capital-intensive manufacturing, commercial transportation, and discretionary consumer retail constituents inside the Dow have faced valuation compression as sticky headline costs and elevated bond yields constrained near-term forward guidance multiples.
The Macro Engine: Crude Oil Around $100 & Shifting Fed Expectations
Quick Answer: Why Did the Dow Jones Fall This Week?
Key drivers behind the weekly selloff included crude oil trading around and above the $100 threshold due to Middle East supply risks and shipping constraints, coupled with shifting bond market expectations that the Federal Reserve may maintain restrictive monetary policy longer to counter energy-driven headline inflation.
Two interrelated macro transmission channels dictated the week’s price discovery:
1. Energy Price Pressures ($100 Threshold)
West Texas Intermediate (WTI) crude traded near and above the psychological $100-per-barrel mark during the week, settling at $100.05 on Friday, while global benchmark Brent settled at $104.61. Elevated oil acts as a direct operational headwind for industrial enterprises—lifting freight, shipping, and raw-material processing charges while reducing discretionary consumer purchasing power.
2. Monetary Policy & Treasury Yield Transmission
Surging energy benchmarks complicate central bank disinflation targets. Fixed-income markets adjusted accordingly, pricing in extended duration for restrictive interest rates, a mechanism analyzed in our guide on interest rates and exchange rates. Rising benchmark Treasury yields pressured price-to-earnings multiples across traditional industrial balance sheets.
Sector Breakdown: What Dragged and What Cushioned the Market
- Weekly Laggards (Industrials, Transport, and Consumer Discretionary): Capital goods producers, freight carriers, and airlines bore heavy selling pressure during the initial four sessions of the week as rising fuel costs threatened upcoming operating margins.
- Defensive Anchors (Energy and Healthcare): Upstream exploration firms benefited from elevated commodity realizations, while pharmaceutical and managed care providers offered defensive capital stability throughout the week.
- The Friday Rebound: The Dow gained over 500 points on Friday as crude oil prices pulled back slightly from their weekly highs and market participants digested latest inflation indicators, offering temporary relief without fully erasing the weekly deficit.
Global Equity Correlation: Wall Street vs. World Indices
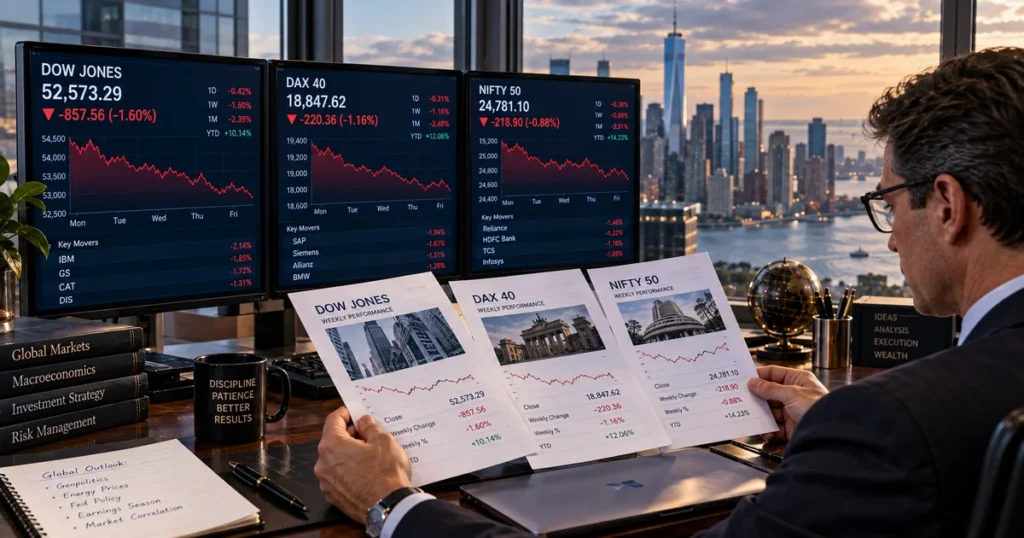
The drop in the Dow Jones this week synchronized with broader global equity pullbacks, reflecting international capital flows examined in our study on fed rate cuts and global liquidity:
| Global Index | Primary Market | Weekly Performance (%) | Core Macro Catalyst |
Dow Jones (^DJI) | United States | -1.6% | Oil price volatility, restrictive rate path |
USA S&P 500 (^GSPC) | United States | -0.8% | Multi-week broad valuation compression |
Germany DAX 40 (^GDAXI) | Germany (Europe) | -1.8% | Industrial input costs, export headwinds |
India Nifty 50 (^NSEI) | India (Emerging) | -2.7% | 5th consecutive weekly decline, FII outflows |
Canada TSX (^GSPTSE) | Canada | -2.3% | Energy and materials exposure partly cushioned the decline |
While commodity-heavy markets such as the Canada TSX also declined during the week, their energy and materials exposure provided some relative support as oil prices remained elevated.
Technical Reference Levels for the Week Ahead
Quick Answer: What Are the Key Chart Levels for the Dow Jones?
Technical reference levels derived from recent multi-month price structures place immediate downside support at 52,200, followed by secondary support near 51,800. Overhead resistance levels are established at 53,100 and 53,650.
- Primary Support (52,200): Represents the lower boundary of the prevailing multi-month ascending trading channel. A sustained daily close below this threshold could trigger additional institutional de-risking toward the 51,800 zone.
- Secondary Support (51,800): Serves as a major structural demand shelf established during previous quarterly consolidation phases.
- Immediate Resistance (53,100): The first technical hurdle required to neutralize immediate short-term selling momentum.
- Major Resistance (53,650): Overhead supply level where the index must achieve sustained volume-backed closes to confirm a resumption of the broader intermediate uptrend.
Frequently Asked Questions
How did the Dow Jones perform this week?
The Dow Jones Industrial Average dropped 1.6% over the week to close at 52,573.29 on Friday, September 11, 2026, marking its worst weekly performance since March 2026 despite a 509.19-point (+0.98%) rebound on Friday.
Why did the US stock market decline this week?
Equities retreated primarily due to crude oil trading around and above $100 per barrel, heightening concerns that elevated energy input costs will sustain inflation and prompt the Federal Reserve to hold interest rates higher for longer.
What is the current trend for the Dow Jones?
The Dow has finished in negative territory in four out of the last five weeks, reflecting continued pressure on cyclical industrials alongside broader defensive positioning.
How did the S&P 500 and Nasdaq close the week?
The S&P 500 closed at 7,656.98, down 0.8% for the week despite an 0.86% gain on Friday. The Nasdaq Composite closed at 26,333.04, logging a 0.7% weekly decline after rallying 0.96% on Friday.
Strategic Summary & Core Takeaways
- Worst Week Since March: The Dow fell 1.6% on the week to 52,573.29, logging its steepest weekly pullback in six months despite a 509-point Friday rally.
- S&P 500 Third Weekly Loss: The S&P 500 dropped 0.8% on the week to 7,656.98, marking its third consecutive weekly decline.
- Oil at the $100 Mark: WTI hovering near $100.05 and Brent at $104.61 reignited inflation concerns, prompting fixed-income markets to reprice rate cut trajectories.
- Synchronized Global Weakness: Major indices across Europe (DAX 40 down 1.8%) and emerging markets (Nifty 50 down 2.7%) exhibited coordinated drawdowns.
- Technical Levels: Key reference levels identified from price structure stand at 52,200 (immediate support) and 53,100 (initial overhead resistance).
Next Reading Suggestions
- USA S&P 500: The Complete Guide to Index Methodology, Market-Cap Weighting, and Global Market Mechanics
- Canada TSX: The Complete Guide to the S&P/TSX Composite Index, Methodology, and Market Structure
- Germany DAX 40: The Complete Guide to Components, Total Return Methodology, and Global Market Mechanics
- Dubai Financial Market (DFM): The Complete Guide to the DFMGI Index, Methodology, and Market Structure
- How Stock Prices Are Determined: Market Microstructure, Supply and Demand, and Valuation
- What Is Market Capitalization? The Complete Guide to Market Cap, Company Size, and Valuation
- Interest Rates and Exchange Rates: The Complete Guide to Global Currency Pricing
- Fed Rate Cuts & Global Liquidity: The Complete Guide to Interest Rates, the Fed Balance Sheet, and Asset Markets
- What Is Gold? The Complete Guide to Real Money, Store of Value & Why It Matters
Author Box & E-E-A-T Verification
Written & Researched By: CurrencyPlans Editorial Research Team
Editorial Review & Market Analysis Standards: This market intelligence report is compiled from verified exchange trading feeds, official cash-market closing numbers, and macroeconomic data releases from the Federal Reserve and U.S. Energy Information Administration. All index data points reflect official Friday closing levels.
Educational References & Market Data Sources
- S&P Dow Jones Indices (DJIA & S&P 500 Data): S&P Dow Jones Indices
- New York Stock Exchange (Market Summary & Official Closing Feeds): NYSE
- Federal Reserve Economic Data (FRED – Macroeconomic Statistics): Federal Reserve
- U.S. Energy Information Administration (Official Petroleum Status): EIA
Educational Disclaimer
This market analysis is prepared strictly for educational, research, and informational purposes and does not constitute personalized financial, investment, trading, or tax advice. Equities, regional market indices, and derivative contracts carry market risks. Past weekly performance does not guarantee future financial returns. Always consult an independent licensed fiduciary advisor before allocating investment capital.

