
Executive Summary & Core Thesis
A currency exchange rate is the price of one sovereign currency expressed in terms of another, establishing the foundational conversion ratio for cross-border commerce, global capital allocation, and foreign exchange trading. In an international financial architecture processing over $9.6 trillion per day in Over-the-Counter (OTC) turnover (as reported by the Bank for International Settlements), exchange rates reflect continuous price discovery across interbank networks, central banks, and electronic execution venues. While exchange rates are quoted in standardized pairs (such as EUR/USD or USD/JPY), their equilibrium levels are determined by an interplay of benchmark interest rate differentials, relative inflation trajectories, current account balances, terms of trade, sovereign debt sustainability, and national exchange rate regime policies.
The Foundational Core: Defining Currency Exchange Rates
In international economics, money is both the asset being bought and the medium used to purchase it. A currency exchange rate expresses the relative value of one sovereign currency against another.
Every cross-border economic transaction—from importing energy commodities and consumer electronics to foreign portfolio investment and overseas remittances—requires an exchange rate calculation to convert values from one domestic currency to another.
| Macro Horizon | Dominant Market Catalyst | Primary Exchange Rate Channel |
| Short-Term (Intraday to Weeks) | Central Bank Announcements, Data Surprises, Risk Sentiment | High-speed interbank repricing and speculative capital flows |
| Medium-Term (Months to Quarters) | Interest Rate Differentials & Sovereign Yield Spreads | Cross-border portfolio allocation and FX carry trade positioning |
| Long-Term (Multi-Year Cycles) | Inflation Differentials, Productivity, & Current Account Balances | Real Effective Exchange Rate realignment and Relative PPP |
Because exchange rates represent a price ratio between two distinct national currencies, a change in an exchange rate always represents simultaneous strength in one currency and weakness in its counterpart.
The Quotation Anatomy: Base Currency, Quote Currency, and Spreads
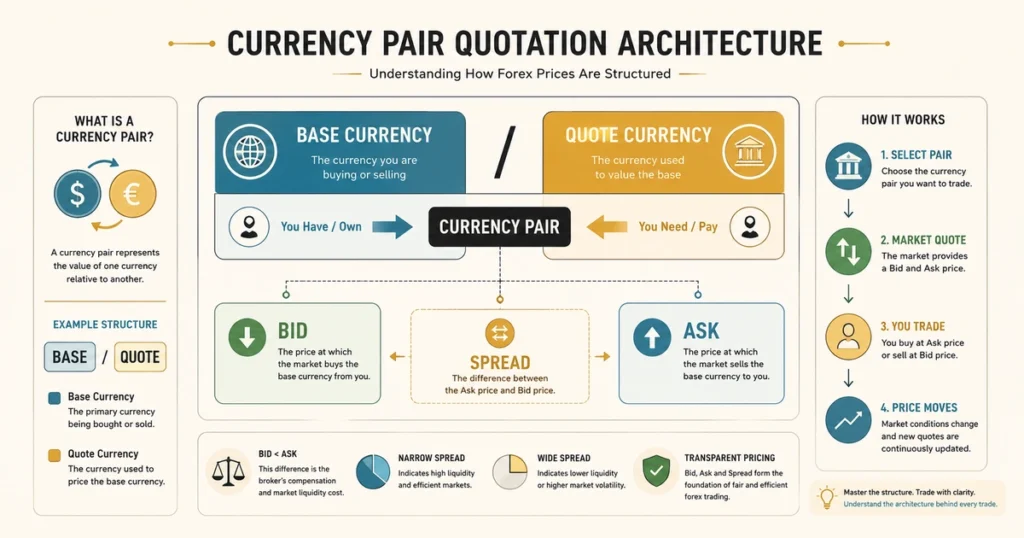
In global foreign exchange markets, exchange rates are quoted in standardized ISO three-letter currency pairs:
$$\text{EUR / USD} = 1.0850$$
+-------------------------------------------------------------------------------+
|                       CURRENCY PAIR QUOTATION STRUCTURE                       |
+----------------------+-----------------------------+--------------------------+
| COMPONENT            | IDENTIFIER                  | ECONOMIC ROLE            |
+----------------------+-----------------------------+--------------------------+
| Base Currency        | EUR (Left side)             | The fixed unit (1 EUR)   |
| Quote / Term Currency| USD (Right side)            | Variable price ($1.0850) |
+----------------------+-----------------------------+--------------------------+
- The Base Currency (Left): Represents the unit being purchased or sold (always equal to 1).
- The Quote Currency (Right): Represents the amount of secondary currency required to acquire one unit of the base currency.
Bid, Ask, and the Spread
Interbank market makers quote two prices simultaneously:
- Bid Price: The price at which the dealer buys the base currency from a market participant.
- Ask (Offer) Price: The price at which the dealer sells the base currency to a market participant.
- The Spread: The mathematical difference between Ask and Bid, representing market-maker compensation and transaction costs.
$$\text{Spread} = \text{Ask Price} – \text{Bid Price}$$
$$\text{Pip Measurement (Standard)} = 0.0001 \quad \text{\vert{} Japanese Yen Pairs} = 0.01$$
Direct vs. Indirect Currency Quotation Conventions
Depending on the geographic location of the market participant and local banking practices, exchange rates are quoted through two distinct conventions:
Direct Quotation
A direct quote expresses the price of one unit of foreign currency in terms of domestic currency units:
$$\text{Direct Quote} = \frac{\text{Domestic Currency}}{\text{1 Unit of Foreign Currency}}$$
- Example (From a US Perspective):
1 EUR = $1.08 USD. If the quote rises to$1.12, the foreign currency has appreciated, and the domestic currency has depreciated.
Indirect Quotation
An indirect quote expresses the price of one unit of domestic currency in terms of foreign currency units:
$$\text{Indirect Quote} = \frac{\text{Foreign Currency}}{\text{1 Unit of Domestic Currency}}$$
- Example (From a US Perspective):
$1 USD = ¥155.00 JPY. If the quote rises to¥160.00, the US dollar has appreciated against the Japanese yen, while the yen has depreciated against the dollar.
$$\text{Mathematical Equivalence:} \quad \text{Direct Quote} = \frac{1}{\text{Indirect Quote}}$$
Cross Rates: Pricing Currencies Without the Dollar
According to the BIS Triennial Survey, the US dollar was on one side of approximately 89.2% of all reported foreign exchange trades. This widespread use makes the dollar a common reference currency in global FX markets. When two non-dollar currencies are traded against one another, their exchange rate can be derived as a cross rate.
Calculating a Cross Rate via Triangular Arbitrage:
Given the exchange rates for EUR/USD and USD/JPY, the cross rate for EUR/JPY is calculated as follows:
$$\text{EUR / JPY} = \text{EUR / USD} \times \text{USD / JPY}$$
- Scenario: If $\text{EUR/USD} = 1.0800$ and $\text{USD/JPY} = 150.00$:
- $\text{EUR / JPY} = 1.0800 \times 150.00 = 162.00 \text{ JPY}$
If institutional quotes diverge from this mathematical equilibrium, interbank algorithmic market makers execute Triangular Arbitrage, buying the undervalued currency path and selling the overvalued path until equilibrium is restored across global execution venues.
The Fundamental Pillars Driving Exchange Rates
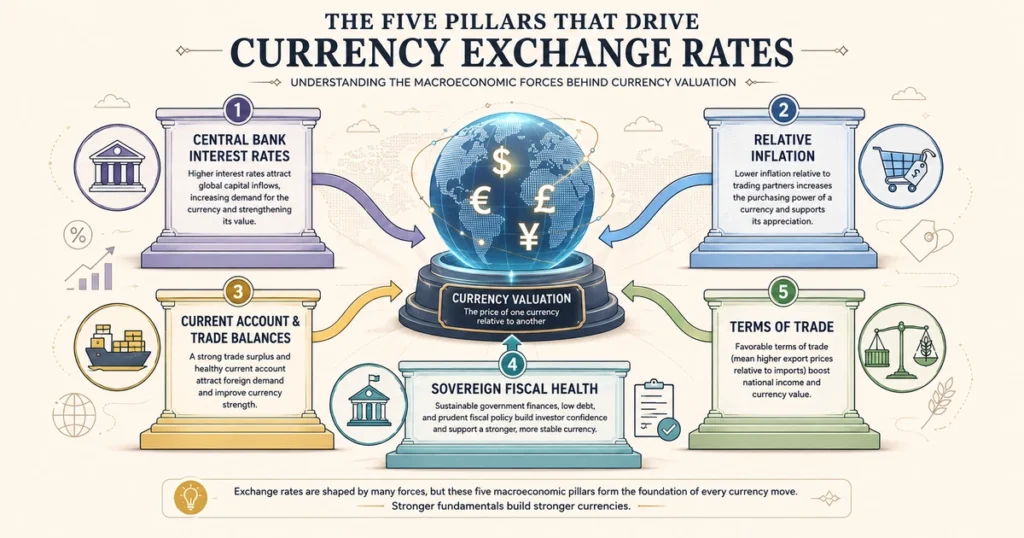
Exchange rate valuations adjust dynamically across global sessions in response to core macroeconomic mechanisms:
                      ┌─────────────────────────────────────────┐
                      │    CENTRAL BANK INTEREST RATES & POLICY │
                      └────────────────────┬────────────────────┘
                                           │
         ┌─────────────────────────────────┼─────────────────────────────────┐
         │                                 │                                 │
         ▼                                 ▼                                 ▼
┌──────────────────┐             ┌──────────────────┐             ┌──────────────────┐
│ INFLATION & PPP  │             │ CURRENT ACCOUNT  │             │ TERMS OF TRADE & │
│  DIFFERENTIALS   │             │  TRADE BALANCES  │             │ FISCAL STABILITY │
└──────────────────┘             └──────────────────┘             └──────────────────┘
- Central Bank Interest Rate Differentials: A relative increase in domestic policy rates can raise yields on domestic fixed-income assets, attracting international capital and supporting the currency, provided inflation expectations remain anchored.
- Relative Inflation Rates (Purchasing Power Parity): Economies experiencing persistently higher inflation than trading partners see domestic purchasing power erode, which tends to lead to downward exchange rate pressure over multi-year horizons.
- Current Account & Balance of Trade: A structural current-account deficit can place downward pressure on a currency over time, though actual exchange rate movements depend heavily on cross-border capital flows and financing conditions.
- Sovereign Fiscal Health & Public Debt: Expanding sovereign debt-to-GDP ratios or unanchored budget deficits can increase risk premia, deter foreign direct investment, and weaken currency valuation.
- Terms of Trade & Commodity Prices: The ratio of export prices to import prices dictates commercial currency demand. Rising export commodity prices support currency appreciation for resource-exporting nations.
Multi-Variable Interaction Matrix: Exchange Rate Responses
The impact of macroeconomic catalysts on exchange rate valuation depends on prevailing global market conditions and regime contexts:
| Macroeconomic Catalyst | Directional Movement | Primary Currency Response | Structural Transmission Channel |
| Monetary Policy Rate | Relative Increase | Upward Support | Widens yield spreads, attracting yield-seeking capital inflows. |
| Domestic Inflation (CPI) | Relative Increase | Downward Pressure | Erodes purchasing power, reducing export competitiveness over time. |
| Trade Balance | Shift toward Surplus | Upward Support | Increases commercial foreign demand for domestic currency settlement. |
| Sovereign Public Debt | Unsustainable Expansion | Downward Pressure | Elevates sovereign credit risk and raises domestic inflation expectations. |
| Global Market Volatility | Acute Risk-Off Shock | Safe-Haven Support | Capital reallocates toward deep, liquid reserve currencies (e.g., USD, CHF). |
Sovereign Exchange Rate Regimes: From Hard Pegs to Free Floats
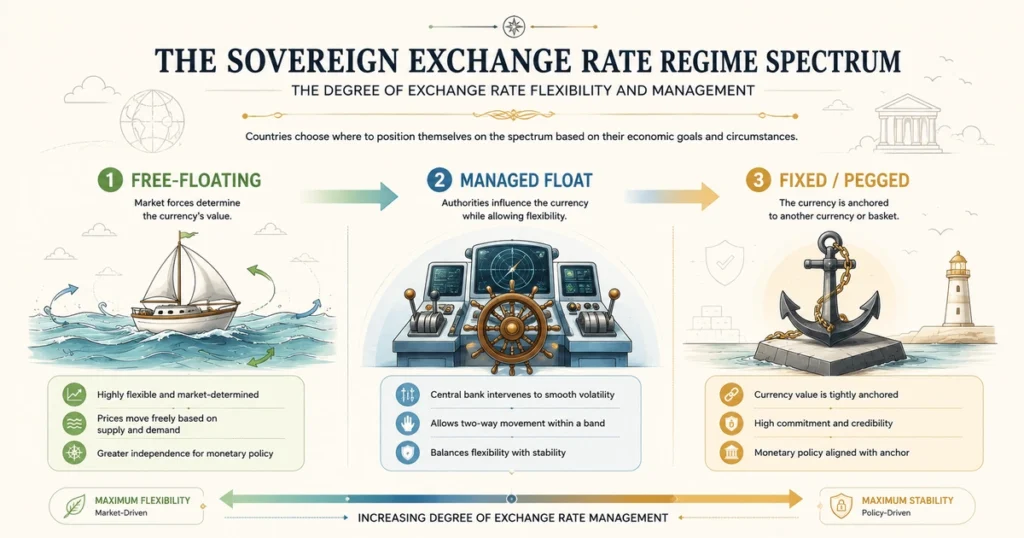
Sovereign central banks manage national currencies using established exchange rate frameworks:
                      ┌─────────────────────────────────────────┐
                      │      SOVEREIGN EXCHANGE RATE REGIMES    │
                      └────────────────────┬────────────────────┘
                                           │
         ┌─────────────────────────────────┼─────────────────────────────────┐
         │                                 │                                 │
         ▼                                 ▼                                 ▼
┌──────────────────┐             ┌──────────────────┐             ┌──────────────────┐
│  FREE-FLOATING   │             │  MANAGED FLOAT   │             │   FIXED / PEGGED │
│  (USD, EUR, JPY) │             │     (INR)        │             │   (HKD, BHD)     │
└──────────────────┘             └──────────────────┘             └──────────────────┘
- Free-Floating Regime: The exchange rate is primarily determined by market supply and demand, although central banks may still intervene during periods of disorderly market conditions or excessive volatility (e.g., USD, EUR, GBP, JPY, AUD).
- Managed / Market-Determined Float: The exchange rate is largely market-determined, while the monetary authority may intervene to address disorderly market conditions or excessive volatility (e.g., Indian Rupee).
- Crawling Peg Regime: The currency is pegged to an anchor currency or basket, with the official parity adjusted periodically in response to inflation differentials or economic indicators.
- Fixed Pegs & Currency Boards: The domestic currency is formally pegged at a fixed exchange rate to an anchor currency, maintained through foreign exchange reserve operations (e.g., Hong Kong Dollar convertibility zone of 7.75–7.85 HKD per USD).
Spot, Forward, and Swap Rates: The Financial Horizon Matrix
Foreign exchange rates are quoted across three primary operational settlement horizons:
| FX Rate Classification | Settlement Horizon | Pricing Determination | Primary Market Objective |
| Spot Exchange Rate | Typically T+1 or T+2 business days, depending on currency pair and market convention | Continuous OTC dealer and electronic-venue price discovery | Immediate cash conversion & trade settlement |
| Forward Exchange Rate | Future settlement date beyond the standard spot value date | Spot Rate $\pm$ Forward Points (Interest Rate Parity) | Corporate cash flow & budget risk hedging |
| FX Swap | Spot + Forward Combined Leg | Interest-rate differentials and forward pricing | Multi-currency liquidity & funding management |
Nominal vs. Real Effective Exchange Rates (REER)
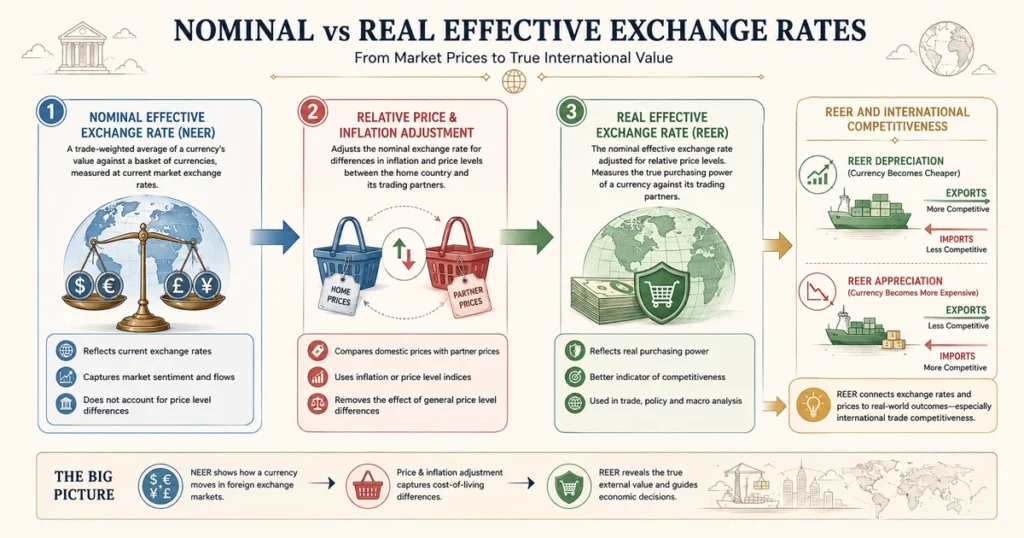
To distinguish between daily currency fluctuations and changes in international trade competitiveness, institutional economists evaluate Real Effective Exchange Rates:
Nominal Effective Exchange Rate (NEER)
The NEER is an unadjusted weighted average of a nation’s currency relative to an index of its major trading partners.
Real Effective Exchange Rate (REER)
The REER adjusts the nominal effective exchange rate for relative price or cost indices (inflation rates) between the domestic economy and its trading partners:
$$\text{REER} = \text{NEER} \times \left( \frac{P_{\text{Domestic}}}{P_{\text{Foreign}}} \right)$$
Where $P$ represents the relevant price indices, with exact weighting conventions determined by statistical reporting institutions.
- Appreciating REER: Indicates that domestic goods are becoming more expensive relative to foreign trading partners, which can reduce export price competitiveness over time.
- Depreciating REER: Indicates that domestic goods are gaining price competitiveness internationally, supporting export volumes.
Macroeconomic Case Dissections: Exchange Rate Shocks
Dissection 1: The Swiss Franc Minimum Exchange Rate Exit (2015)
- Macroeconomic Background: The Swiss National Bank (SNB) had maintained a floor of
1.20 CHF per EURto prevent deflationary pressures and protect export competitiveness. - The Policy Shift: On January 15, 2015, the SNB discontinued the minimum exchange rate.
- Market Response: The Euro fell sharply against the Swiss Franc within minutes. Interbank market liquidity declined significantly, resulting in pricing gaps and substantial losses across international brokerages and institutional funds.
- Core Takeaway: Fixed pegs and exchange rate floors carry structural tail risk when fundamental macroeconomic pressures make central bank balance sheet expansion unsustainable.
Dissection 2: Cross-Border Corporate Exchange Rate Hedging
- Macroeconomic Background: An industrial manufacturing corporation based in the Eurozone exports machinery to North American clients, with long-term contracts invoiced in US Dollars.
- The Exposure: A depreciation of the US Dollar relative to the Euro reduces the local-currency revenue realized by the European exporter.
- Execution: The corporate treasury executes Outright Forward Contracts, locking in future exchange rates to protect operating margins from foreign exchange volatility.
Institutional FX Risk Management Under Volatile Exchange Rates
Corporate treasuries and institutional portfolio managers utilize established risk-management strategies to navigate exchange rate volatility:
- Forward Contract Hedging: Using OTC forward contracts to lock exchange rates for future cash flows and reduce transaction-exposure risk from currency movements.
- Currency Options Collars: Purchasing put options while selling call options to establish a defined exchange rate corridor, limiting downside exposure at reduced cost.
- Natural Hedging: Aligning foreign-currency revenues with foreign-currency operational expenses and local debt issuance to minimize net foreign currency exposure.
- Cross-Currency Swaps: Converting long-term debt liabilities from one currency into another to optimize international borrowing costs and manage exchange rate risks.
Frequently Asked Questions (Institutional FAQ)
What is the fundamental difference between a spot exchange rate and a forward exchange rate?
A spot exchange rate is the price for immediate currency delivery (settling according to standard market convention, typically within one to two business days). A forward exchange rate is agreed upon today for settlement on a specific future date, calculated from the spot rate and the interest rate differential between the two currencies according to Covered Interest Rate Parity.
How do central banks influence national currency exchange rates?
Central banks influence exchange rates through monetary policy rate adjustments, forward guidance, and direct foreign exchange interventions (buying or selling domestic currency using foreign exchange reserves).
Why do currency exchange rates fluctuate continuously?
Exchange rates fluctuate continuously because of changing market expectations regarding central bank interest rates, inflation data releases, trade flows, fiscal debt announcements, and global geopolitical risk sentiment across 24-hour interbank trading networks.
What is the difference between nominal exchange rates and the Real Effective Exchange Rate (REER)?
A nominal exchange rate is the quoted market price ratio between two currencies. The Real Effective Exchange Rate (REER) is a trade-weighted index that adjusts nominal rates for inflation differentials among major trading partners, measuring authentic cross-border trade competitiveness.
What is a currency spread?
A currency spread is the difference between the Ask (offer) price at which a market maker sells a currency and the Bid price at which they purchase it. The spread represents the transaction cost of the trade and dealer compensation.
Strategic Summary & Institutional Takeaways
Understanding currency exchange rates is essential for evaluating international trade flows, sovereign monetary policy, and global portfolio allocation.
While exchange rates represent the price ratio between currency pairs in daily over-the-counter markets, their equilibrium trajectories are governed by real interest rate differentials, relative inflation rates, current account balances, and national exchange rate regimes.
By analyzing quotation conventions, monitoring macroeconomic drivers, and evaluating Real Effective Exchange Rates, corporate treasurers, macro analysts, and investors can better interpret foreign exchange markets and manage international financial risks.
Next Reading Suggestions
- [Understanding Real Effective Exchange Rates (REER) in Global Trade]
- [Central Bank Interventions: Mechanics of Sovereign Currency Management]
- [Purchasing Power Parity (PPP): Theory, Evidence, and Applications]
- [The Structural Role of the US Dollar as the Global Anchor Reserve Asset]
Author Box & E-E-A-T Verification
Written By: CurrencyPlans Financial Research Team
Fact-Checked & Reviewed By: Senior Institutional Market Analyst & FX Strategist
Editorial Integrity & Research Standards: CurrencyPlans publishes institutional-grade research grounded in verified macroeconomic data. All exchange rate frameworks, reserve statistics, and central bank metrics are cross-referenced with primary multilateral institutions including the International Monetary Fund (IMF), the Bank for International Settlements (BIS), and sovereign central banks.
Primary Institutional References & Official Resources
For verified central bank reference rates, macroeconomic research, and global trade frameworks, consult official institutional sources directly:
- Global FX Turnover & Market Structure Data: Bank for International Settlements (BIS) Triennial Central Bank Survey
- International Financial Statistics & Exchange Rate Portals: International Monetary Fund (IMF) Data Portal
- US Foreign Exchange Rates & Benchmark Releases: Board of Governors of the Federal Reserve System Foreign Exchange Data (H.10)
- Euro Foreign Exchange Reference Rates: European Central Bank (ECB) Reference Rates
- Swiss Monetary Policy & Exchange Rate Assessments: Swiss National Bank (SNB) Monetary Policy
Educational Disclaimer
This guide is prepared strictly for educational, informational, and research purposes and does not constitute financial, investment, legal, or tax advice. Foreign exchange rates and monetary policy frameworks fluctuate based on global economic conditions. Always perform independent due diligence and consult a licensed financial advisor before making international financial commitments.

