

The capital allocation pipelines of European finance did not achieve institutional dominance by chance. They were forged through structural experiments, devastating systemic shocks, and massive technological leaps that continuously rewrote the rules of engagement for market participants. To truly grasp how institutional order flow, index arbitrage, and structural liquidity operate in the contemporary environment, one must examine the deep, iterative layers defining the ftse 100 index.
What began as a localized tracking initiative in the United Kingdom has transformed into a highly liquid, electronic benchmark closely monitored by global foreign institutional investors (FIIs). This transition was not a smooth progression, but rather a chaotic evolution propelled by intense market crises, structural exploits, and pivotal regulatory overhauls. For institutional desks, algorithmic traders, and market makers, reviewing the trajectory of the ftse 100 index provides critical insights into order flow mechanics, value areas, and systemic liquidity transitions.
Every modern protocol, from the calculation of the continuous mathematical free-float calculation to high-speed order routing at the London Stock Exchange (LSE), directly descends from these historical inflection points. Tracing this unique lineage reveals how the democratization of electronic data systematically dismantled physical, floor-based monopolies, permanently shifting global liquidity dynamics and turning the United Kingdom equity complex into an elite vehicle tracking massive institutional wealth.
Featured Snippet Block
The ftse 100 index officially began its operational tracking on January 3, 1984, in the United Kingdom, created as a joint venture between the Financial Times and the London Stock Exchange (hence FTSE). Developed to track the structural health of the UK’s top-tier corporate landscape, the ftse 100 index originally established a base level of 1,000 points, managing a dynamic basket of the 100 most highly capitalized companies listed in London.
Key Takeaways from the History of the FTSE 100 Index
- Pioneered Capitalization-Weighting: Shifted Europe away from primitive arithmetic stock averages toward free-float market capitalization.
- Survived Systemic Crises: Endured massive structural market crashes, geopolitical splits, and intense currency liquidations.
- Maintained Global Commodity Exposure: Evolved into a unique blue-chip index heavily dominated by international mining, energy, and banking giants.
- Democratized European Wealth: Accelerated institutional and retail order flow convergence across global electronic systems.
The Structural Origins: How and Why Was the ‘Footsie’ Created?
1801 to 1984: Transitioning Beyond Manual Price Tracking at the LSE
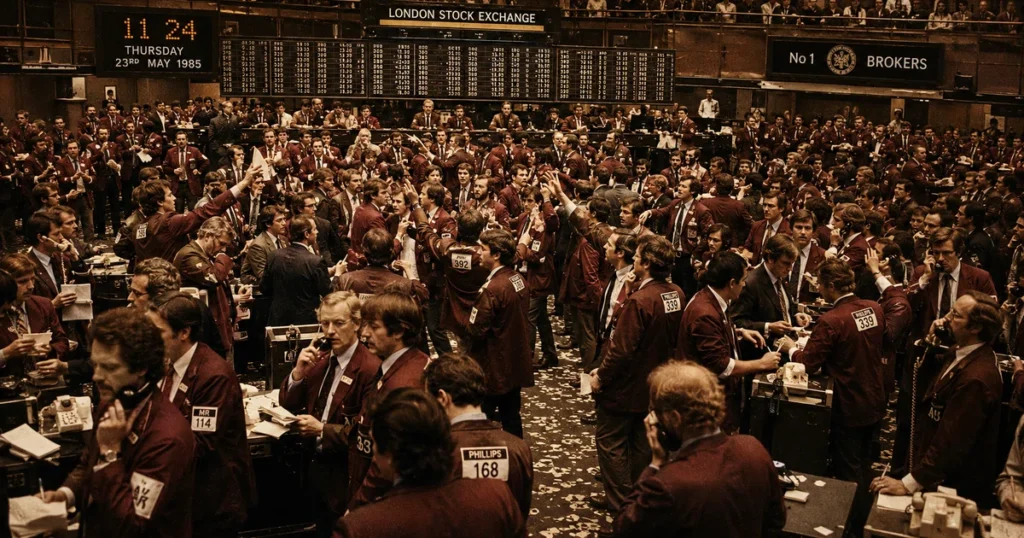
Long before automated order matching systems or digital clearing houses existed, price discovery in Western markets occurred through raw human interaction. For nearly two centuries, the London Stock Exchange operated without a dynamic, real-time index optimized for modern institutional portfolios. The older FT 30 index was mathematically restricted and failed to reflect the massive waves of capital pouring into the UK. This structural vacuum prompted the development of the ftse 100 index, a tool designed to convert volatile market noise into a highly reliable, liquid mathematical signal. The early deployment of the ftse 100 index changed the game, replacing old manual tracking loops with a continuous calculation framework that updated prices minute by minute.
The Initial Blueprint: Tracking the Top 100 Corporate Giants
To establish a statistically valid baseline for the United Kingdom economy, the selection committee isolated the 100 most liquid, heavily capitalized enterprises. The design parameters of the ftse 100 index dictated that only the elite elite corporate entities could maintain a position in the basket. Over time, as domestic manufacturing gave way to massive multi-national energy giants, banking conglomerates, and pharmaceutical titans, the composition of the ftse 100 index shifted dynamically. This flexible, quarterly rebalancing protocol ensured that the index never became stagnant, allowing it to serve as the definitive benchmark for pricing Western European equity risk.
The Defining Shockwaves: Systemic Crises that Transformed UK Microstructure
1987 Crash and the ‘Big Bang’ Technology Transition
The structural integrity of London’s capital pipeline faced a devastating, brutal stress test shortly after its inception. The October 1987 market crash injected massive, aggressive panic into the equity market. A closer inspection of the order book during this period reveals an absolute liquidity vacuum, causing severe distress across the entire UK capital complex. As global selling accelerated, the ftse 100 index plummeted violently, exposing the critical vulnerabilities of floor-based brokers who simply refused to answer their physical telephones as prices collapsed.
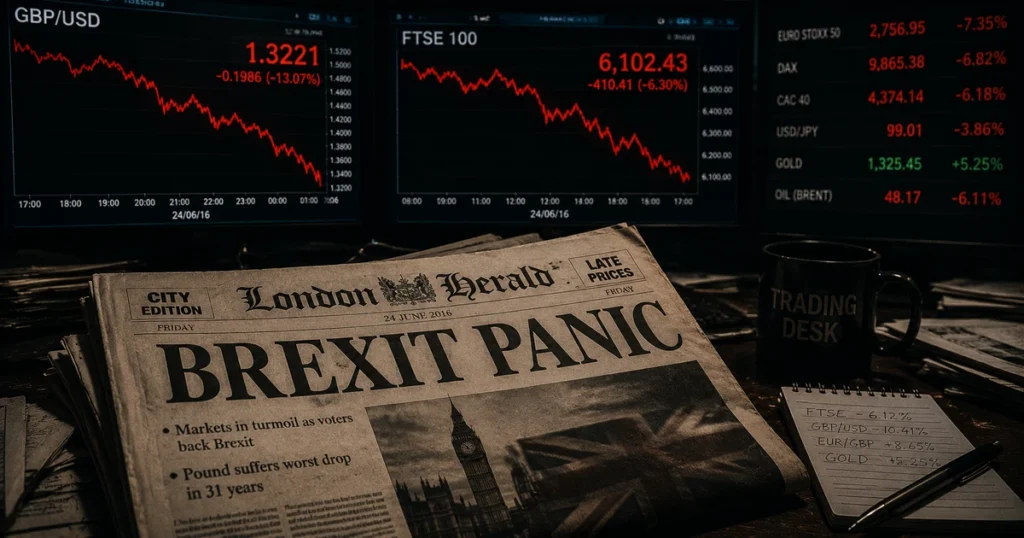
This violent era forced the London Stock Exchange to aggressively accelerate its structural transition. Dubbed the “Big Bang,” the exchange completely deregulated its markets, eliminated fixed commission floors, and transitioned the entire processing framework of the ftse 100 index onto automated, screen-based electronic systems. This technological mutation permanently altered market microstructure by mandating electronic data transparency, paving the way for modern algorithmic market makers to provide continuous passive liquidity.
The 2016 Brexit Referendum: When Politics Triggered a Passive Liquidity Sweep
On June 23, 2016, the United Kingdom voted to leave the European Union, triggering an immediate, catastrophic systemic shock across global trading terminals. When the early referendum voting data hit the wires, the overnight order books faced unprecedented, brutal liquidations. The ftse 100 index experienced wild, violent intraday swings as foreign institutional investors rapidly repriced the value of British corporate assets against a crashing British Pound ($GBP$).
Because many constituents inside the ftse 100 index derive their revenues from international markets in US Dollars, the currency devaluation actually triggered an aggressive, massive automated buying wave in large-cap exporters. This counter-intuitive market movement highlighted the complex global nature of the ftse 100 index, proving to global macro funds that the index acts more like an international liquidity vehicle than a localized domestic tracker.
The Modern Retailing Epoch: How Global Funds Dominated UK Flows
The ETF Revolution and the Rise of Passive FII Capital
As digital execution technology advanced into the late 1990s and early 2000s, the introduction of exchange-traded funds tracking the ftse 100 index completely transformed public capital allocation. Common retail participants suddenly realized they could trade all 100 blue-chip components simultaneously with a single mouse click. The launch of these highly liquid passive tracking products became a massive onboarding point, bringing a continuous wave of retail capital that permanently altered the daily volume profiles of the index.
The Shift to Global Diversification and Commodities Exposure
A unique characteristic that developed across the modern history of the ftse 100 index is its high concentration of multi-national mining, oil, and financial giants. Unlike the tech-heavy benchmarks in the United States, global capital flows into the ftse 100 index are often driven by asset allocators seeking a structural hedge against inflation. When global commodity cycles turn bullish, massive institutional order flow routes directly into London’s top-tier mining and energy conglomerates, lifting the entire value area of the index.
Market Microstructure: How the Modern FTSE 100 Index Functions
Market Capitalization Weighting: A More Representative Structure than the Dow Jones
A major architectural feature of the ftse 100 index is its reliance on free-float market capitalization weighting. Unlike price-weighted systems where a single high-priced stock can completely distort the index value, the ftse 100 index ranks its constituents based on the actual aggregate market value of their available shares.
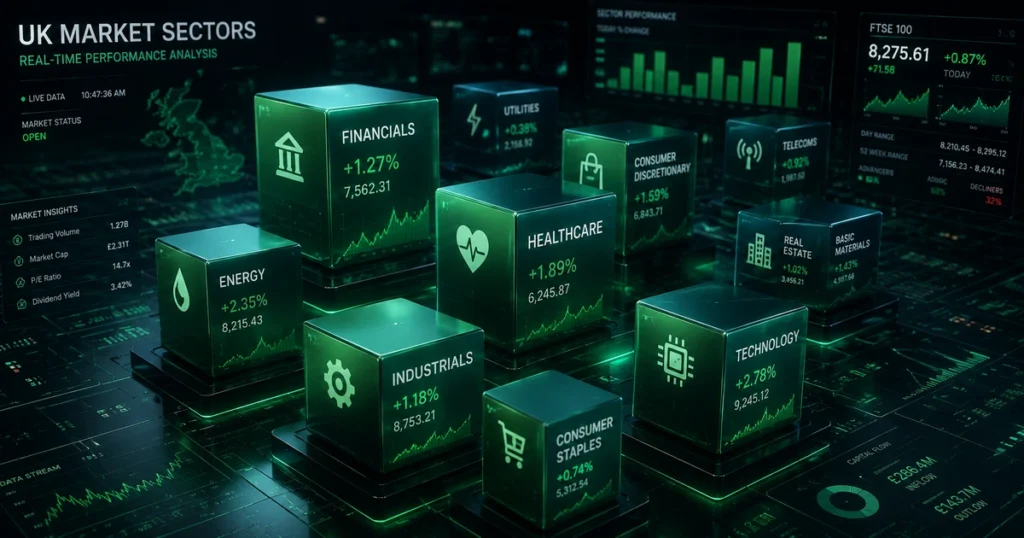
This ensures that a corporate giant’s true economic scale dictates its mathematical impact on the benchmark. In the calculation framework of the ftse 100 index, every stock’s weight is continuously recalculated based on its floating equity capitalization. This structural design provides a highly accurate, undistorted visual representation of overall market health, protecting the mathematical data integrity of the index from artificial price gaps caused by individual stock splits.
| Benchmark Era | Calculation Methodology | Primary Order Routing | Structural Risk Factors |
| 1984 Launch Era | Early Cap-Weighted Flow | Open Outcry / Telephones | Manual Price Update Latency |
| Post-1987 Big Bang | Screen-Based SEAQ System | Electronic Terminal Routing | Early Programmatic Trading Loops |
| 2000 Dot-Com Bubble | Free-Float Capitalization | Central Electronic Order Book | Extreme Tech-Valuation Bubbles |
| Modern Algorithmic Era | Automated Float Processing | Co-located HFT Matching Nodes | Algorithmic Liquidity Sweeps, Flashes |
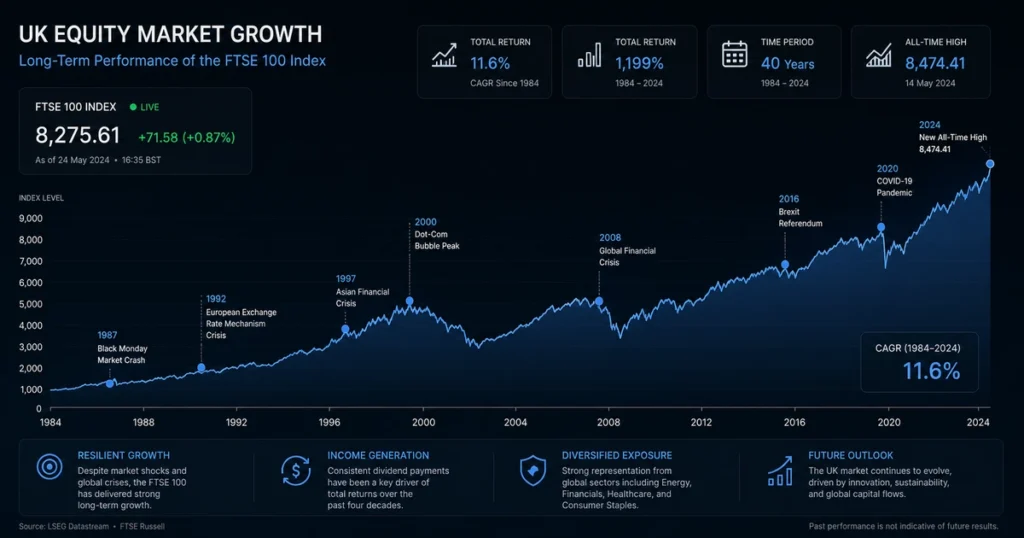
Comparative Analysis of Top Historical Volatility Events
The long-term trajectory of the London market serves as a stark visualization of global macroeconomic shifts. Every single major structural support and resistance level tested over the decades reflects a distinct phase of underlying institutional capital rebalancing tracked continuously within the ftse 100 index.
[Retail Brokers / Apps]       [Institutional Desks]        [High-Frequency Algos]
           │                            │                            │
           ▼                            ▼                            ▼
   [FIX Protocol Layer]       [Direct Market Access]       [Co-located Server Nodes]
           │                            │                            │
           └────────────────────────────┼────────────────────────────┘
                                        ▼
                           [LSE SETS Matching Engine]
                                        │
                          ┌─────────────┴─────────────┐
                          ▼                           ▼
            [Price-Time Priority Base]   [Free-Float Cap Adjustments]
                          │                           │
                          └─────────────┬─────────────┘
                                        ▼
                        [Real-Time FTSE 100 Index Print]
                                        │
                                        ▼
                        [Dissemination to Global Feed]
Frequently Asked Questions About the History of the FTSE 100 Index
What exactly does the ‘FTSE’ in the index name stand for?
FTSE stands for the Financial Times and the London Stock Exchange. The two entities formed a specialized joint venture in 1984 to create a dynamic, real-time market capitalization weighted index that could accurately track the top tiers of British corporate equity.
How often are the components of the index reviewed and changed?
The components of the index are reviewed on a quarterly basis by an independent selection committee. Companies that have dropped significantly in market value are removed, while rapidly growing enterprises are promoted into the basket to maintain an accurate representation of the market.
Is the index a true indicator of the domestic UK economy?
Not entirely. While the companies are listed in London, a massive percentage of the total revenue generated by the index constituents comes from international operations outside the UK. This makes the index highly sensitive to global commodity prices and foreign exchange fluctuations.
How does a free-float market capitalization system protect the index from distortion?
A free-float system only counts the shares that are actively available for public trading, excluding government holdings or insider blocks. This ensures that the mathematical weight of a company in the index accurately reflects the actual liquid equity available to public investors.
What was the structural impact of the 1986 ‘Big Bang’ on the index?
The Big Bang completely modernized the trading infrastructure of the index by eliminating floor-based monopolies. It shifted London into a borderless electronic market, massively increasing liquidity, lowering transaction costs, and allowing global algorithmic funds to participate directly.
Terminal Wrap-Up & Discussion
Analyzing the structural layers of the ftse 100 index proves that market architecture must continuously evolve to survive global macroeconomic realities. The index has successfully morphed from an early terminal tracking experiment into an ultra-fast, world-class digital data pipeline. For modern algorithmic traders and long-term asset allocators, understanding these deep layers of operational history is absolutely vital to successfully navigating global market volatility.
How is your trading framework optimizing for the unique commodity and international currency exposure presented by the top constituents inside Europe’s most liquid benchmarks? Let us know your workflow strategies in the comments below.
Educational Financial Disclaimer
This article is written entirely for educational, research, and historical context. It does not constitute financial advice, investment recommendations, or an endorsement to buy or sell any specific asset class. Equities carry high levels of structural risk and volatility. Past historical performance is never an indicator of future market results.

